MCA or BCA?
How a Clothing Retailer Found Repayments That Match Its Seasons
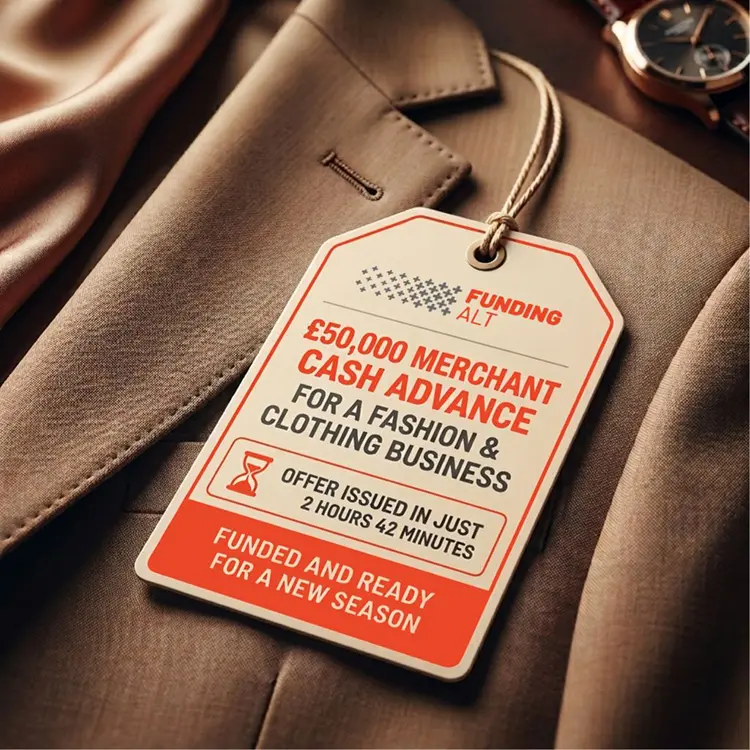
A clothing retailer applied for a BCA with fixed repayments, but uneven revenue made it a poor fit. We moved it to a £50,000 Merchant Cash Advance with repayments that flex with sales.
The product you apply for isn’t always the right one. A recent case shows how looking at a business’s cash flow led to a better fit than the application it started with.
The case in brief
A long-established clothing retailer applied to us for a BCA (Business Cash Advance), expecting fixed repayments. Their revenue, though, rose and fell sharply through the year.
We reviewed their cash flow, saw card terminal receipts running through it, and talked them through a Merchant Cash Advance instead.
Repayments could then move with their busy and quiet periods.
- Funding: £50,000 Merchant Cash Advance (MCA)
- Diversion Split: 8% of their daily card sales
- Time to offer: 2 hours and 42 minutes
- Result: Funded on time for the new season
Why a fixed repayment didn’t quite work
The retailer’s income isn’t steady. Sales build up around key points in the calendar and then slow down. A BCA asks for the same repayment each time, whatever the month looks like. That is simple and predictable, but in a slow month a fixed repayment can take a bigger bite out of cash flow than the business is comfortable with.
Fixed repayments suit businesses with steady, predictable income. When your revenue swings between very high and very low, they can leave you stretched in the quiet months and under-using your cash in the busy ones.
What we noticed
When we went through the retailer’s cash flow, we saw that a large share of its income came through a card terminal. That mattered. An MCA is repaid as a share of card takings, so a business with regular card receipts can often use one successfully. We raised it with the owners, talked through how it would work, and agreed that it was a better fit than the product they had applied for.
How an MCA changed the repayments
With an MCA, repayments are taken as a share of card takings, so they rise and fall with sales:
- In a busy season: takings are higher, so more is repaid and the advance clears faster.
- In a quiet season: takings are lower, so the repayment is smaller and the pressure on cash flow eases.
For this retailer, that meant the repayments followed their fast and slow seasons, not a fixed schedule that ignored them. The funds arrived in time for the new season.
BCA or MCA: which is right for you? | ||
Description | BCA | MCA |
Repayments | Fixed and predictable | Flex with your card sales |
Best suited to | Steady, consistent income | Uneven or seasonal income with regular card takings |
Things to consider | A fixed amount is due even in a quiet month | Needs a regular flow of card receipts |
Neither is better in every case. The right one depends on how your business actually trades. If you’ve applied for funding and the repayments don’t sit right, it is worth asking whether a different product would fit better but we’ll do our best to identify if there is a more suited option.
What is a Merchant Cash Advance?
A Merchant Cash Advance gives your business a lump sum, which is repaid as a share of your future card takings. Repayments move with your sales, so a quieter week means a smaller repayment.
Is an MCA right for you?
An MCA may suit you if:
- Your revenue goes through busy and quiet periods
- You take a good share of your income by card
- You need fast access to working capital
- You want repayments that flex with your trading
Talk to us
To find out which product could suit your business, contact the Funding Alternative team today. We’ll look at how you actually trade before recommending anything.
For more information on how an MCA can solve your seasonal cashflow problems, read our blog.